
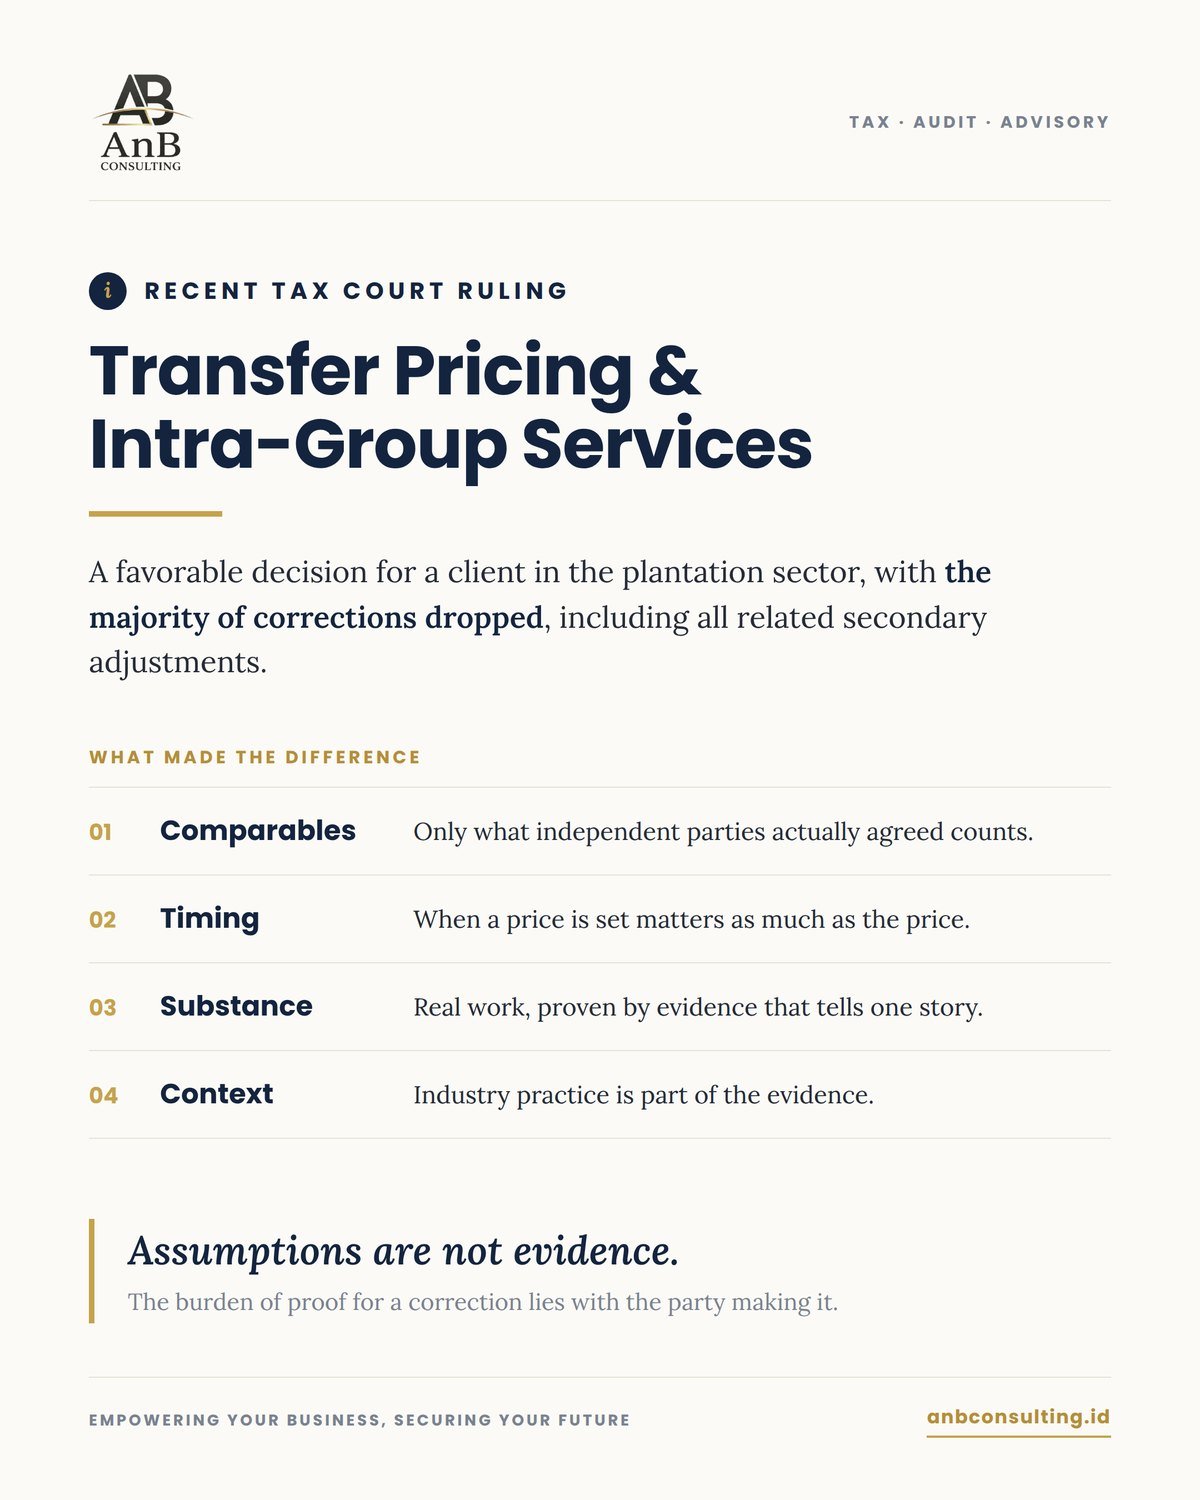
Our team at AnB recently secured a favorable Tax Court decision for a client in the plantation sector, with the majority of the corrections dropped, including all related secondary adjustments.
The dispute centred on transfer pricing and intra-group services. These cases are rarely won on big arguments alone. They are won on whether the facts can hold up under scrutiny.
What this case reminded us of
- A comparable is only as good as the transaction behind it. Under the CUP method, not every number on a market report reflects what independent parties actually agreed.
- When a price is set matters as much as the price itself. In fast-moving markets, comparing figures from the wrong moment can make a fair price look unfair.
- Existence and benefit are proven by substance, not just paperwork. Imperfect documents do not erase real work, as long as the evidence tells a consistent story.
- Business practice deserves to be understood before it is judged. Context is part of the evidence.
Assumptions are not evidence.
The court also reaffirmed a principle worth remembering: the burden of proof for a correction lies with the party making it.
A lesson from the points we did not win
Not every point went our way, and that is a lesson too. Where the law requires a specific formal document, substance alone is not enough. Preparation starts long before the dispute does.